Request a Demo

CLOUSYS · CONNECTED PROFESSIONAL SERVICES

Invoicing & Billing

Connect approved work, commercial validation and invoice readiness.
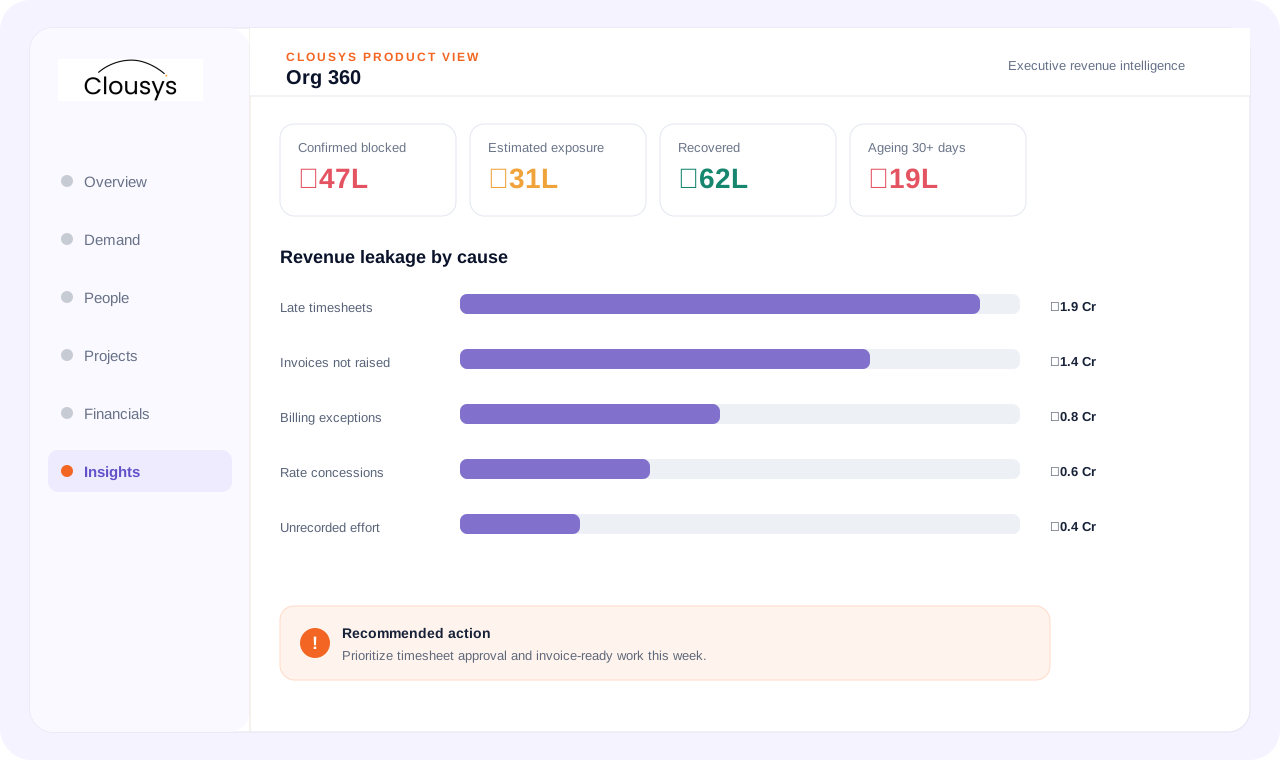
Revenue, Billing and Profitability interface illustration
Illustrative product view · sample data, not a performance claim

THE DECISION THIS SUPPORTS

Make invoice readiness a shared responsibility.

Work is complete, but an approval or commercial exception is unresolved. Give delivery and finance the same evidence and a clear owner for the item blocking invoice preparation.

Revenue with an operational basis

Build the forecast from work that can realistically be staffed and delivered.

Keep opportunity assumptions, committed work and billing expectations distinguishable. When a date or allocation changes, review the downstream revenue effect instead of updating the finance forecast independently of delivery.

REVENUE WITH AN OPERATIONAL BASIS
  • 01Committed work
  • 02Forecast assumptions
  • 03Delivery dates

Time approval and billing readiness

Understand where delivered work sits in the approval chain.

Submitted time, approved work with an exception and invoice-ready value represent different operational states. Give each state an owner and next action so finance can move work forward without repeatedly requesting the same context.

TIME APPROVAL AND BILLING READINESS
  • 01Submitted time
  • 02Approval status
  • 03Invoice-ready work

Commercial exceptions

Review billing exceptions against the engagement’s agreed terms.

Rate discrepancies, purchase-order constraints and missing approvals require different resolution paths. Keep the reason and accountable owner visible; a single unbilled total does not explain which decisions will release the value.

COMMERCIAL EXCEPTIONS
  • 01Rates
  • 02Purchase-order constraints
  • 03Exception ownership
SEE IT IN CONTEXT

Explore this workflow with your team’s priorities.

Book a focused walkthrough

Confirmed leakage versus estimated exposure

Keep confirmed blocked revenue separate from modelled exposure.

Confirmed amounts should be traceable to transactions; estimates depend on explicit assumptions. Adding both into one total can mislead decision-makers and obscure whether an intervention is resolving an existing blockage or preventing a possible one.

CONFIRMED LEAKAGE VERSUS ESTIMATED EXPOSURE
  • 01Transaction evidence
  • 02Model assumptions
  • 03Separate totals

Ageing and prioritization

Review how long value has remained blocked and the cause of the delay.

Prioritize aged, material exceptions with the teams able to resolve them. A useful finance view makes the next action visible and lets leaders distinguish an unresolved approval from an invoice already progressing normally.

AGEING AND PRIORITIZATION
  • 01Days blocked
  • 02Value at risk
  • 03Resolution priority

Project margin drivers

Examine effort, staffing costs, rates and delivery variance alongside the project’s expected revenue.

A headline margin percentage is an outcome, not a diagnosis. Trace the variance to operational drivers before deciding whether to change the staffing mix, address scope or revisit the remaining estimate.

PROJECT MARGIN DRIVERS
  • 01Cost and effort
  • 02Rate realization
  • 03Remaining estimate

Recovery tracking

Track value that was blocked and has moved into invoicing.

Define the event counted as recovery so it is not confused with cash collected. Review recovered value alongside new blockages and ageing; a strong month of recovery can otherwise mask recurring upstream problems.

RECOVERY TRACKING
  • 01Resolved exceptions
  • 02Invoice progress
  • 03New blockages

Delivery–finance review

Bring delivery owners and finance into one review of project economics and billing readiness.

Agree which exceptions can be resolved now, which need client input and which require leadership decisions. Carry the owner and target date into the next review rather than reopening the same discussion.

DELIVERY–FINANCE REVIEW
  • 01Shared review
  • 02Decision owner
  • 03Resolution date

PRACTICAL QUESTIONS

Questions about invoicing & billing.

When is delivered work ready to invoice?

Completion alone is not enough. Check that the relevant time or milestone is approved and that rates, purchase orders and other commercial requirements are satisfied. Invoice-ready work should be distinguishable from work still awaiting review.

Why separate confirmed blockers from estimated exposure?

Confirmed blockers should be traceable to transactions. Estimated exposure depends on assumptions, such as unrecorded allocated effort. Combining the two can imply a level of certainty that the underlying evidence does not support.

Does recovered value mean cash collected?

Not necessarily. A recovery measure may refer to blocked work that has become invoice-ready or invoiced. Define the event clearly and track cash collection separately if that is the financial outcome being measured.

Discuss your requirements ↗
THE LATEST FROM CLOUSYS

Ideas for your next operating decision.

View all insights →